It is the last day of November and all the companies had released the Quarter Result. This is the last one that i had been waiting for... And in this post, i will include some of the findings that i find in the Annual Report 2015. You can refer to my first post on MIKROMB posted on 26 October 2015, by clicking this link,
http://gainvestor10sai.blogspot.my/2015/10/mikromb-bomb-kaboom.html
1. Fundamental Analysis:
 |
| MIKROMB Q1 2016 Result |
MIKROMB announces their First Quarter Result today, in the last day of November and also their Annual Report 2 weeks ago in November.
 |
| Revenue and Net Profit |
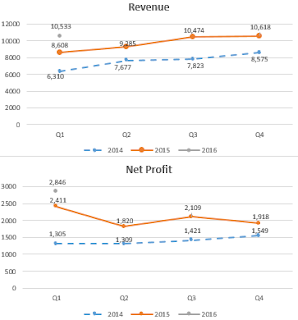
Let's talk about quarterly result first. By comparing with the same quarter, the revenue increased 22.36% due to the increase in sales. Not much surprise in net profit as it increased 18.04%[2]. So, for me, as long as the revenue and net profit is improving, then i think the business model is excellent. One thing to note here in the commentary on prospects, the current weakening of RM against USD is beneficial to MIKROMB in near term as the receivables in USD from oversea sales is higher than the payable in USD.
However, if the condition continues for a long run, MIKROMB will suffer because 63% of the revenue is derived from local sales. Mostly projects had been delayed to one or two years due to the slow economy. The management will intensify the efforts to improve oversea sales. As we can see from the charts on the left, the revenue and net profit are leading and growing every year. MIKROMB is a net cash company with 0.03 net cash per share. The average net profit margin from 2011 to 2015 is 17.82% while every year, the net profit margin exceeds 13%, which is a magnificent for a company like this.
Now let's take a look at the chairman statement in the Annual Report 2015. Export sales improved 67% to overseas market (Vietnam, India, Indonesia and Australia). MIKROMB is beginning to benefit from the brand equity and reputation. Their products are receiving the recognition from the global market. Latest landmark projects, such as KLIA 2, SP Setia HQ, Sunway Pyramid 3 and IOI Shopping Mall 2 at Putrajaya[3]. All of these projects are quite new, established in this year. As the business gathers momentum, MIKROMB need to expand capacity in order to fulfill anticipated sales demands and prevent stunting revenue growth due to capacity constraints[1]. They had acquired a vacant production factory which was approved on 6 November. While focusing at the domestic market, they will make more even inroads into oversea markets.